Marvell’s $70–90 Billion Ambition Raises the Bar for AI Infrastructure
Bottom lineMarvell’s increased fiscal 2028 outlook points to stronger connectivity demand. Its $70–90 billion fiscal 2031 target puts customer diversification, production delivery and cash generation under a sharper test.
Marvell’s new growth targets make the strongest commercial case for owning more of the infrastructure around AI computation. They also create a demanding execution test. The most useful near-term signal is the acceleration in connectivity demand, while the much larger fiscal 2031 ambition depends on years of customer deployments, supply-chain delivery and disciplined spending.
At its October 6 Investor Day in New York, Marvell raised its fiscal 2028 revenue outlook to approximately $20 billion, from $18 billion in August. Management also set a fiscal 2031 revenue target of $70 billion to $90 billion. These are forward-looking company targets, not contracted revenue or results already achieved.
The $2 billion increase in the nearer-term outlook deserves close attention. Management attributed it to connectivity, including optical interconnects and switching. That is a more specific signal than a general claim that AI spending remains strong: Marvell expects the systems connecting processors to generate more business than it previously anticipated.
More compute increases the value of moving data
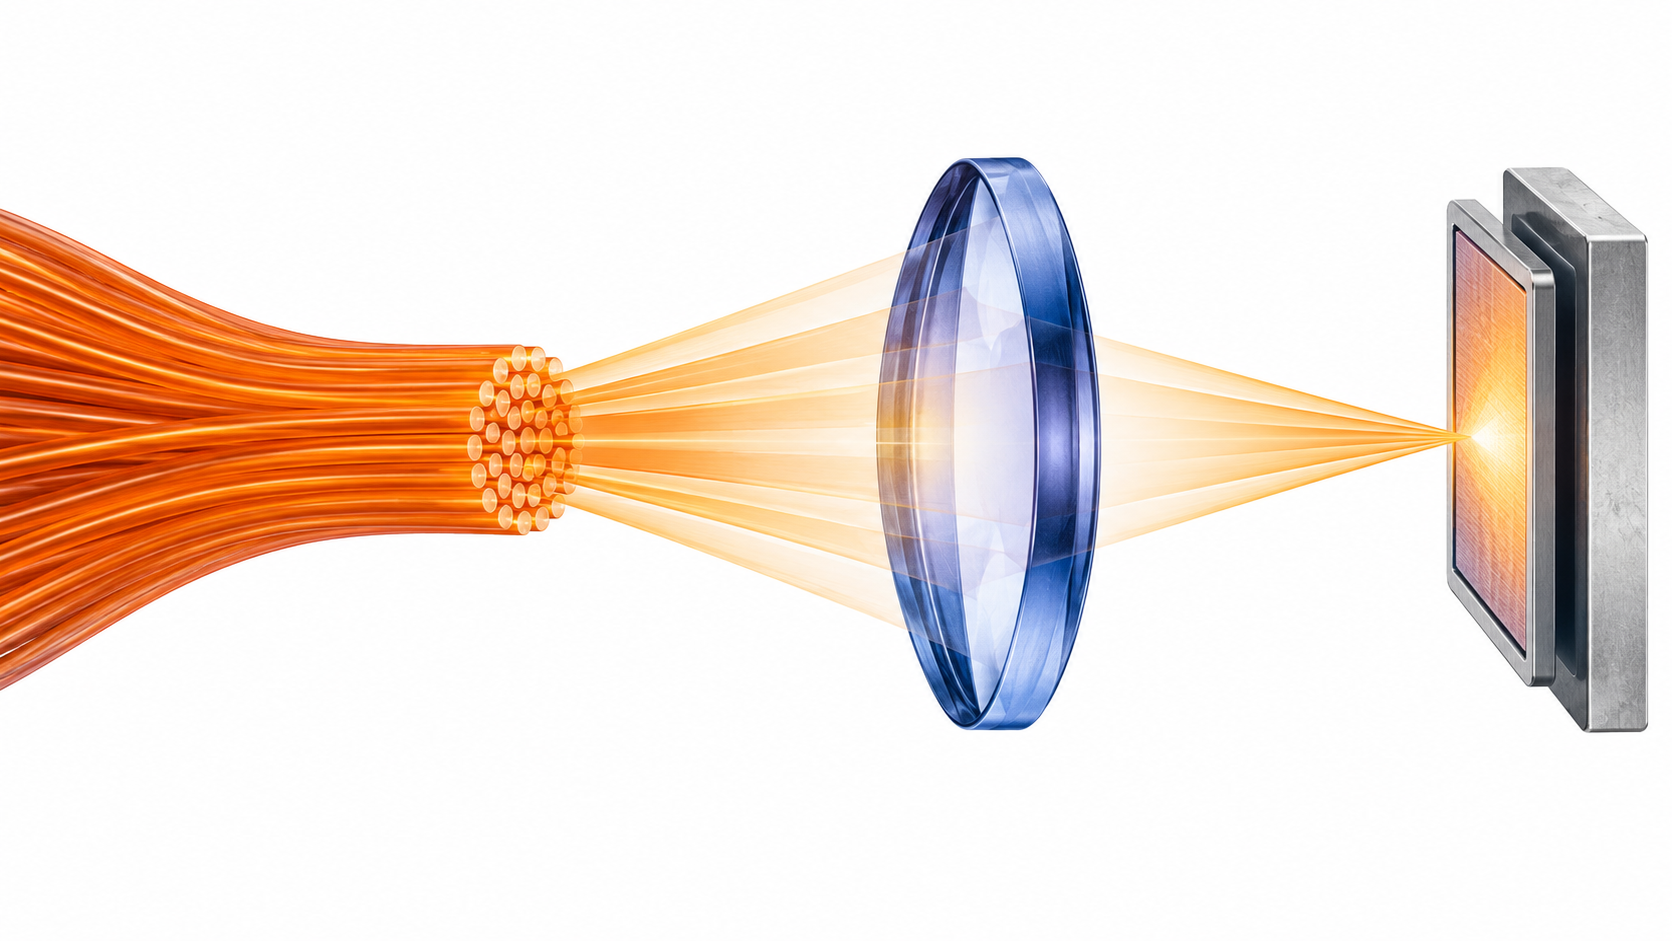
AI infrastructure has to deliver useful work across a whole system. Adding processors achieves less if communication leaves them waiting. The commercial opportunity for networking and optical suppliers therefore depends on how architectures evolve, alongside the number of accelerators purchased.
Marvell’s recent optical demonstrations illustrate the direction of its product development: higher-bandwidth links and technologies designed to reduce power per bit. Demonstrations establish technical progress and ambition. They do not establish volume shipments, customer acceptance or future margins.
Our interpretation is that investors and infrastructure buyers should examine the amount of connectivity required per deployment. A supplier can expand its business when a system needs more sophisticated connections, even if the growth rate of aggregate computing expenditure moderates. That possibility helps explain the strategic significance of the revised outlook without assuming every long-term target will be reached.
Diversification has to be tested at the customer level
Marvell sells across several infrastructure functions, including custom chips, interconnects, switching and storage. Multiple products can create more routes into a customer’s architecture and reduce dependence on any single component.
Yet product diversity does not automatically create independent demand. Several product lines can still depend on the same small group of large customers, the same construction schedules and the same AI investment cycle. If a major deployment moves, demand for several components may move together.
This is the less comfortable implication of the expansion story. Becoming deeply embedded in customer systems can make a supplier more valuable while also increasing the consequences of a customer’s delay. The relevant evidence is the spread of production programs and revenue contributions, rather than the number of product categories in a presentation.
A bigger revenue model needs a bigger operating system
Marvell’s management discussed investing ahead of growth to reserve manufacturing capacity. That is commercially understandable: a design opportunity has limited value if the company cannot deliver the required chips. It also means demand assumptions influence commitments before the associated revenue is recognized.
The key question is how these commitments compare with customer obligations and expected cash generation. The public outlook alone does not establish that all projected demand is covered by non-cancellable orders. Nor does it show that capacity, packaging and product qualification will align perfectly across every program.
Margin analysis needs similar care. Different products can contribute different gross margins, development costs and cash requirements. A change in mix can improve total earnings even while a headline percentage declines. Conversely, rapid sales growth can disappoint economically if spending and delivery costs grow faster than expected.
What would change the assessment
The case strengthens with quarterly evidence that connectivity growth is converting into shipments, custom programs are entering production and cash generation is keeping pace with expansion. Clearer disclosure on customer concentration and capacity commitments would make the long-term framework easier to evaluate.
The case weakens if deployment delays recur, product transitions require more spending than expected or customers capture most of the economic benefit through pricing pressure.
FUVISIGHT’s conclusion is that Marvell has made connectivity a more consequential part of the AI business story. Its fiscal 2031 range provides a map of management’s ambition. The fiscal 2028 increase provides a closer milestone against which that ambition can be judged. Progress through those nearer milestones will carry more analytical weight than repeatedly quoting the largest number.
References
- Marvell, “Marvell Investor Day 2026,” official event page, October 6, 2026. · Source dates preserved in reference title
- Marvell management, Investor Day remarks, October 6, 2026; transcript hosted by Stock Analysis. · Source dates preserved in reference title
- Reuters, “Marvell raises 2028 revenue forecast on strong AI data center demand,” published October 6, 2026, 10:11 a.m. EDT; syndicated by StreetInsider. · Source dates preserved in reference title
- Marvell, “Marvell to Showcase Industry-First 2nm Optical Technology Demos for AI Data Center Infrastructure at ECOC 2026,” September 2026. · Source dates preserved in reference title